The Mortgage Journal
Practical guides, rate updates, and mortgage strategy for Toronto buyers and homeowners.
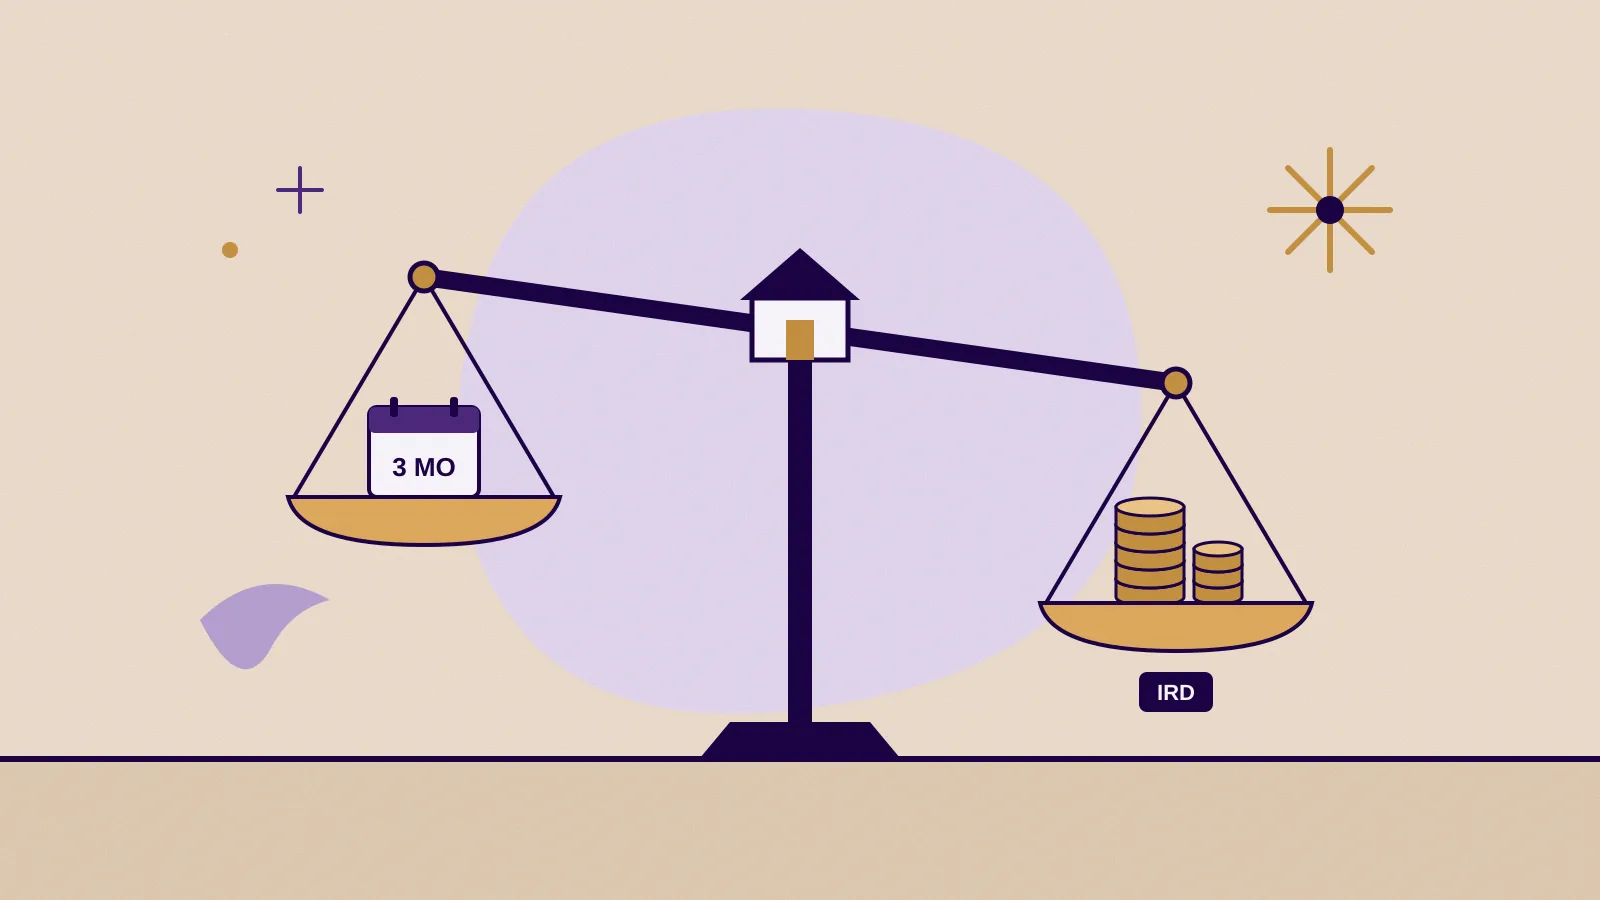
Breaking Your Mortgage Early? How Prepayment Penalties Are Calculated
Selling, refinancing or switching before your term ends can trigger a penalty of three months' interest or an IRD. Here's how lenders calculate it, with a GTA example.
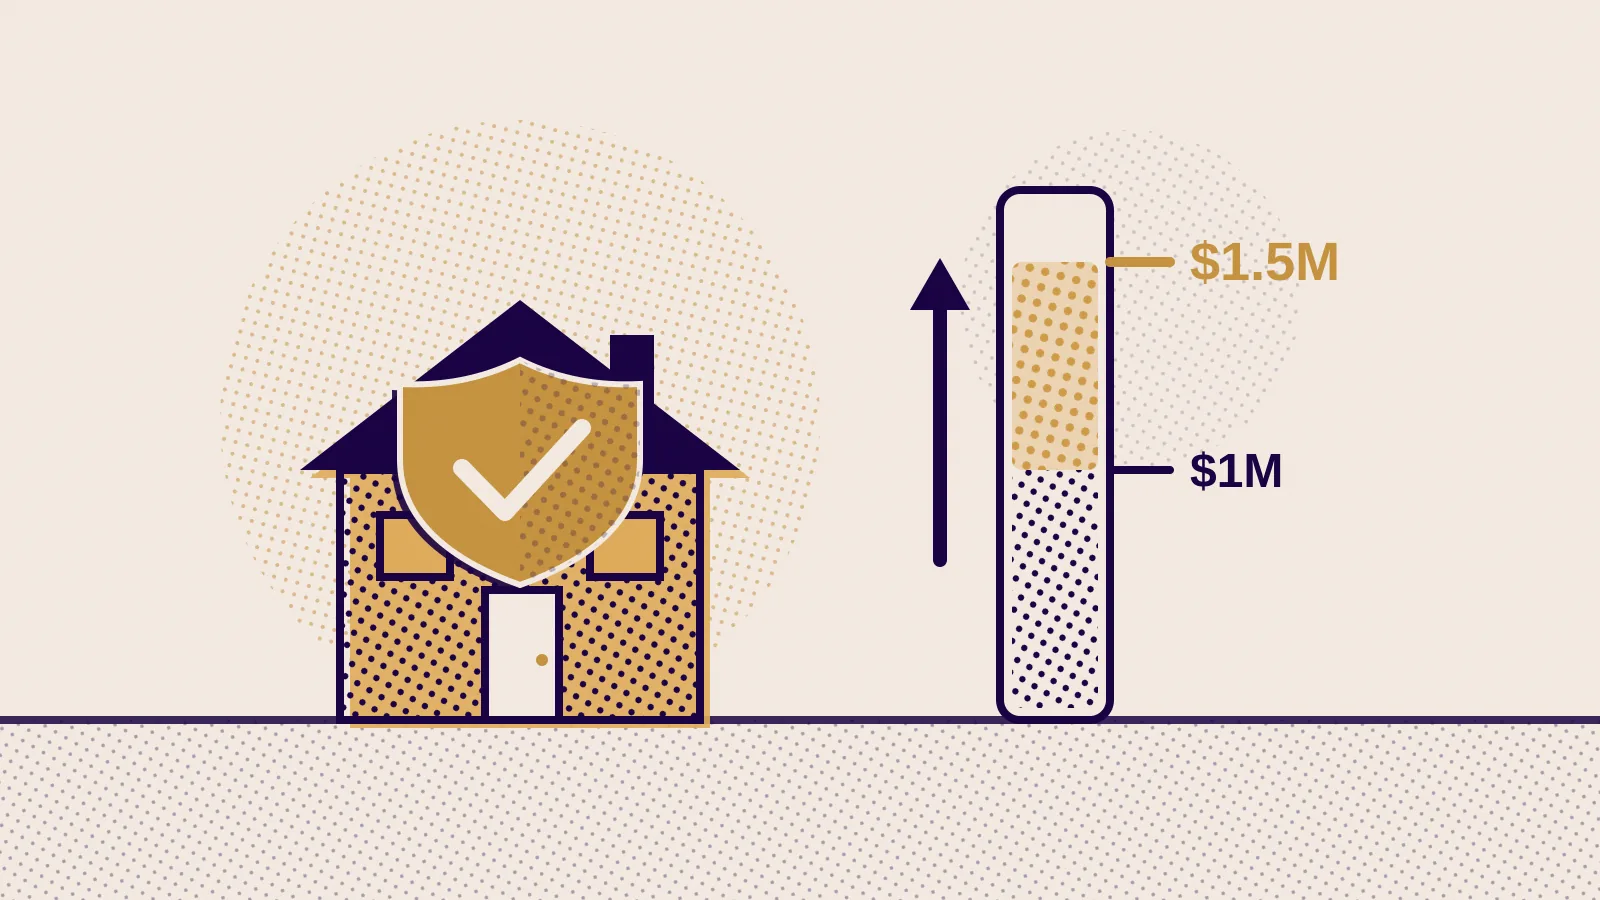
Putting 20% Down on a $1M+ Home? What Budget 2026's Insurance Change Means
Budget 2026 proposes letting 20%-down mortgages on homes up to $1.5 million be insured, with 30 years for first-time buyers and new builds. Here's what it could mean in the GTA.
Insured Financing for New Triplexes and Fourplexes: What Toronto Owners Should Know
From February 1, 2027, new triplexes and fourplexes can get insured loans up to 90% with no price cap. Here's what it means in Toronto, where fourplexes are allowed city-wide.
October Inflation Held at 3.1%: What It Means for Your Mortgage
Inflation held at 3.1% in October, but excluding gasoline it stayed at 2.2% and Ontario came in at 2.5%. Here's what it means for rates and for how much you qualify for.
Adding a Basement Apartment in Brampton: Rules, Costs and Financing
Brampton's ARU registration and rental licensing rules, CMHC's 90% secondary suite refinance, and how suite rent helps you qualify, with numbers at today's prices.
Trigger Rates After the Hike: How Close Is Your Variable Mortgage?
With prime at 4.70%, fixed-payment variable borrowers are asking about trigger rates. Most are far from theirs, but their amortization is quietly growing.
Toronto Land Transfer Tax for First-Time Buyers: What You Pay at Today's Prices
Buying in the City of Toronto means two land transfer taxes. Here is what first-time buyers actually pay after both rebates, worked out at October 2026 Toronto prices.
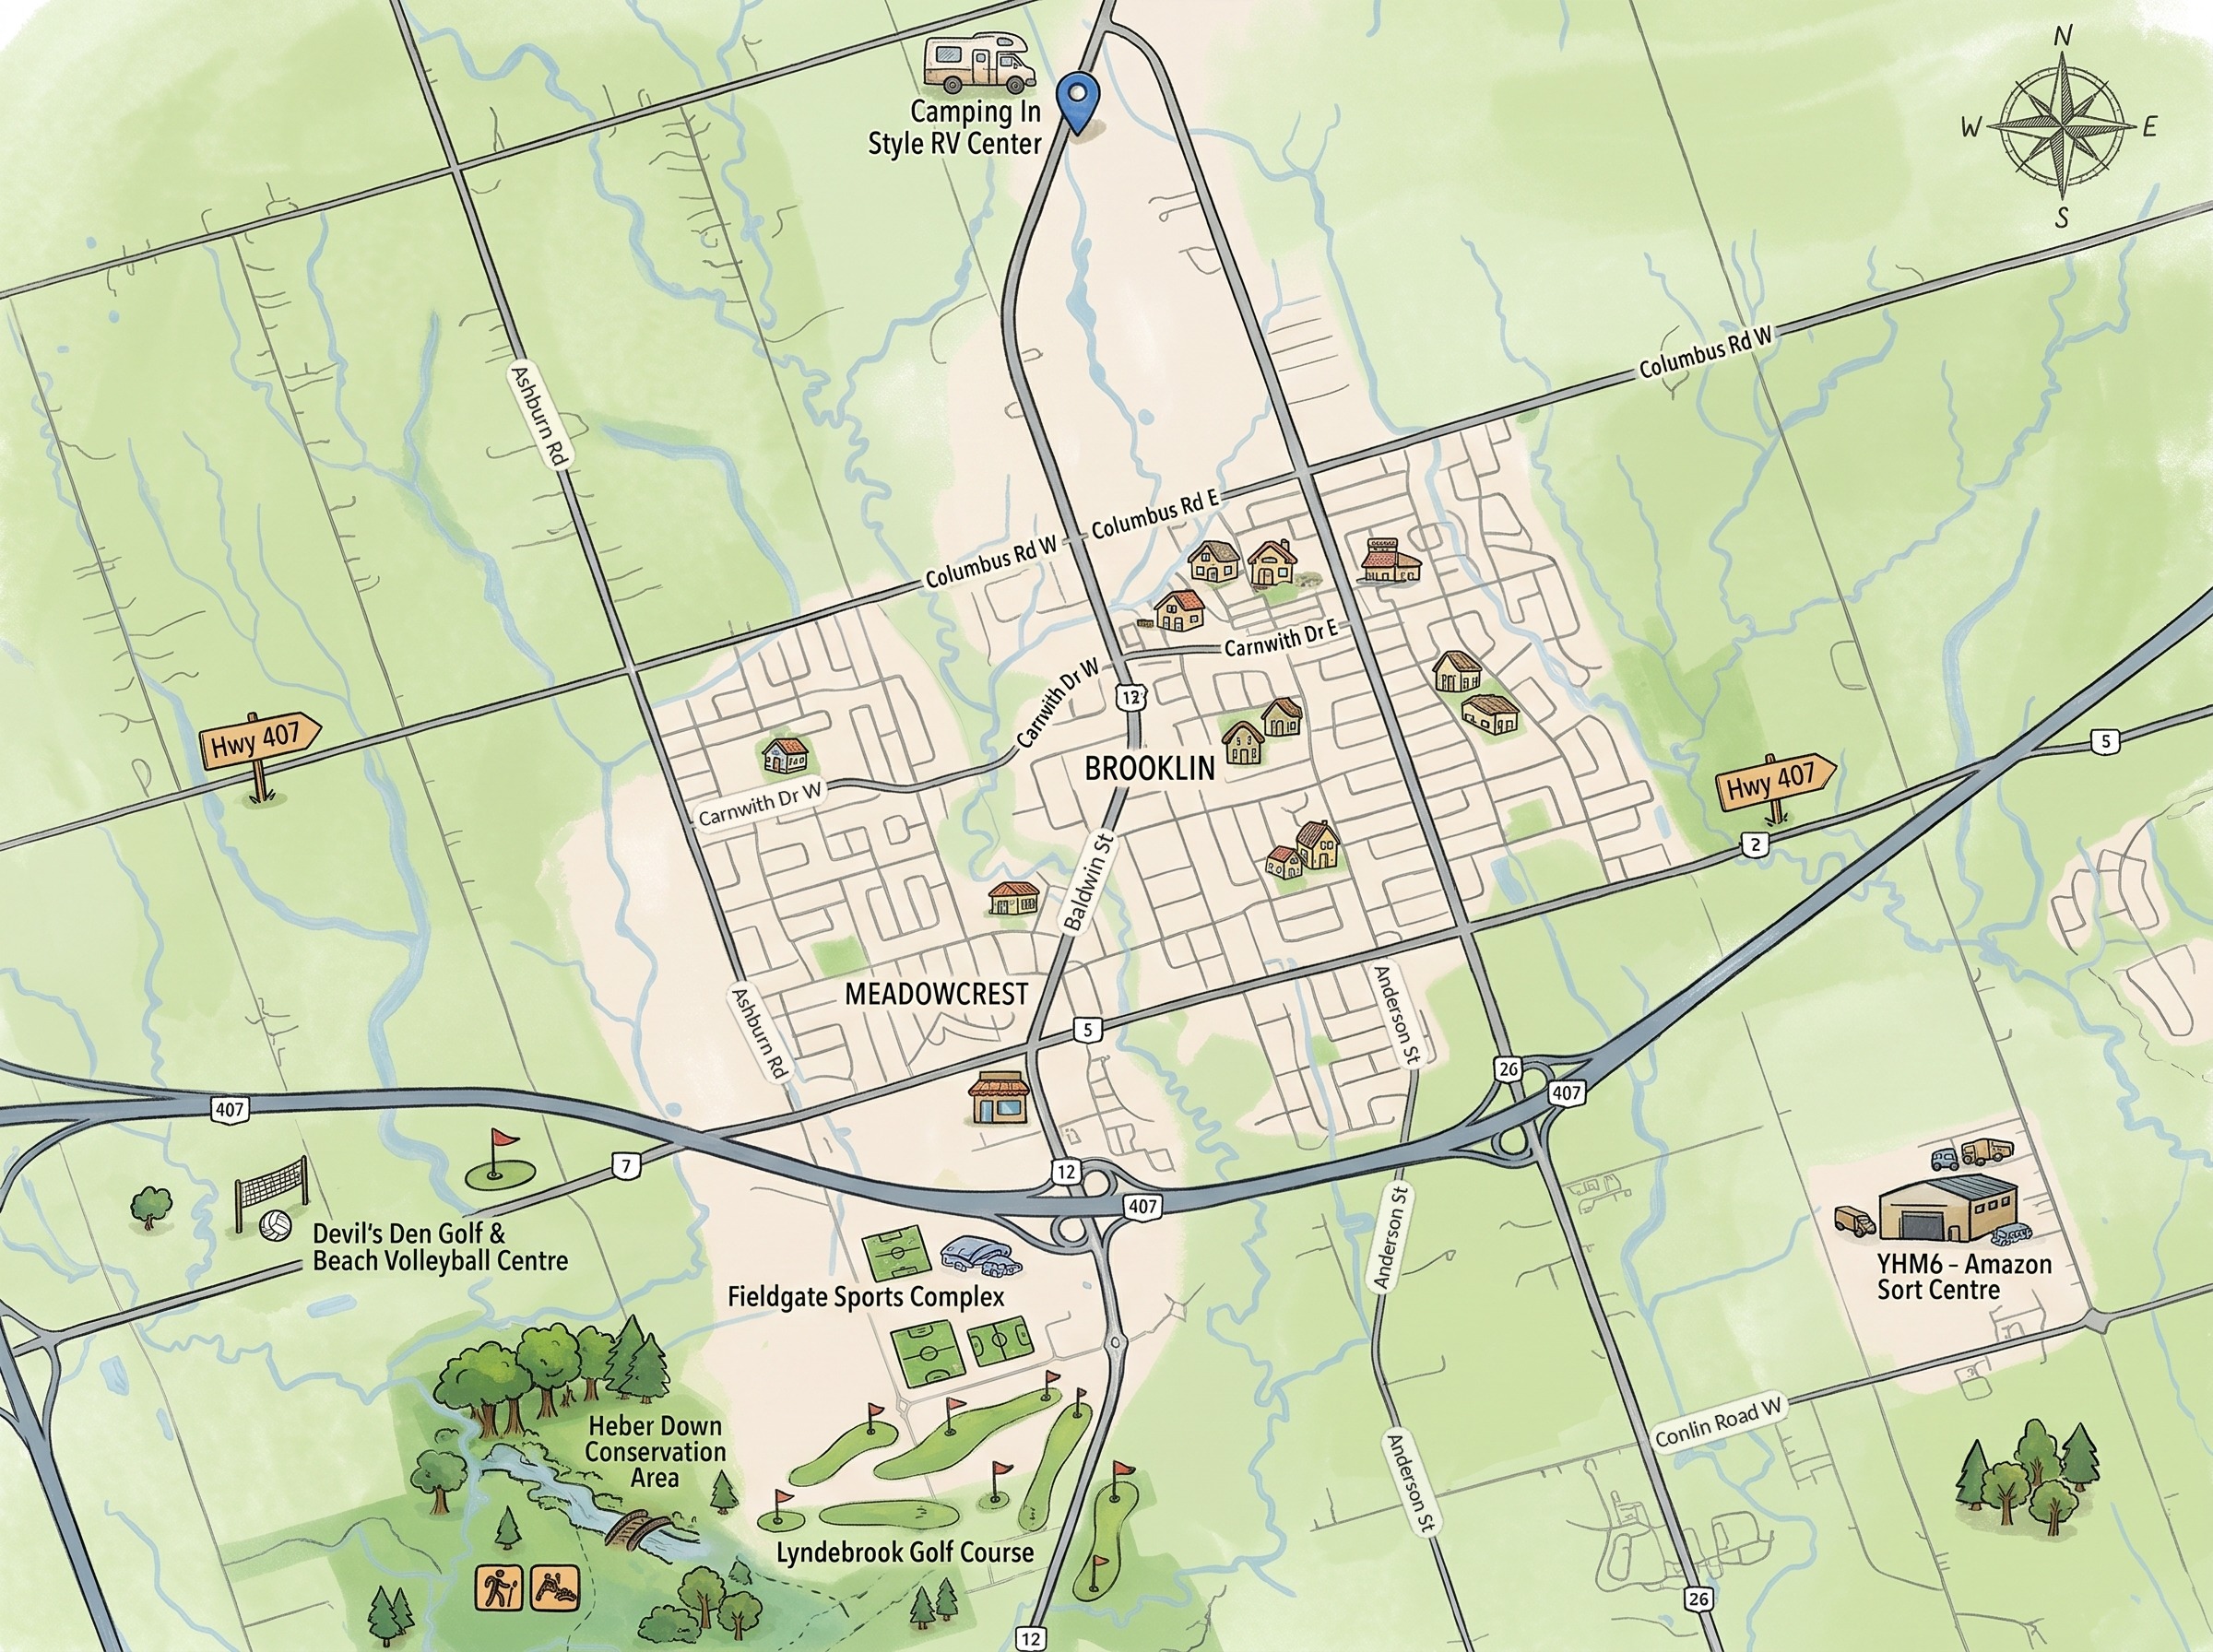
Brooklin, Durham: What Homes Cost Now and What Is Being Built
Brooklin home prices for October 2026, the new home projects under way, and what Whitby's growth plans mean for your mortgage, resale or new.
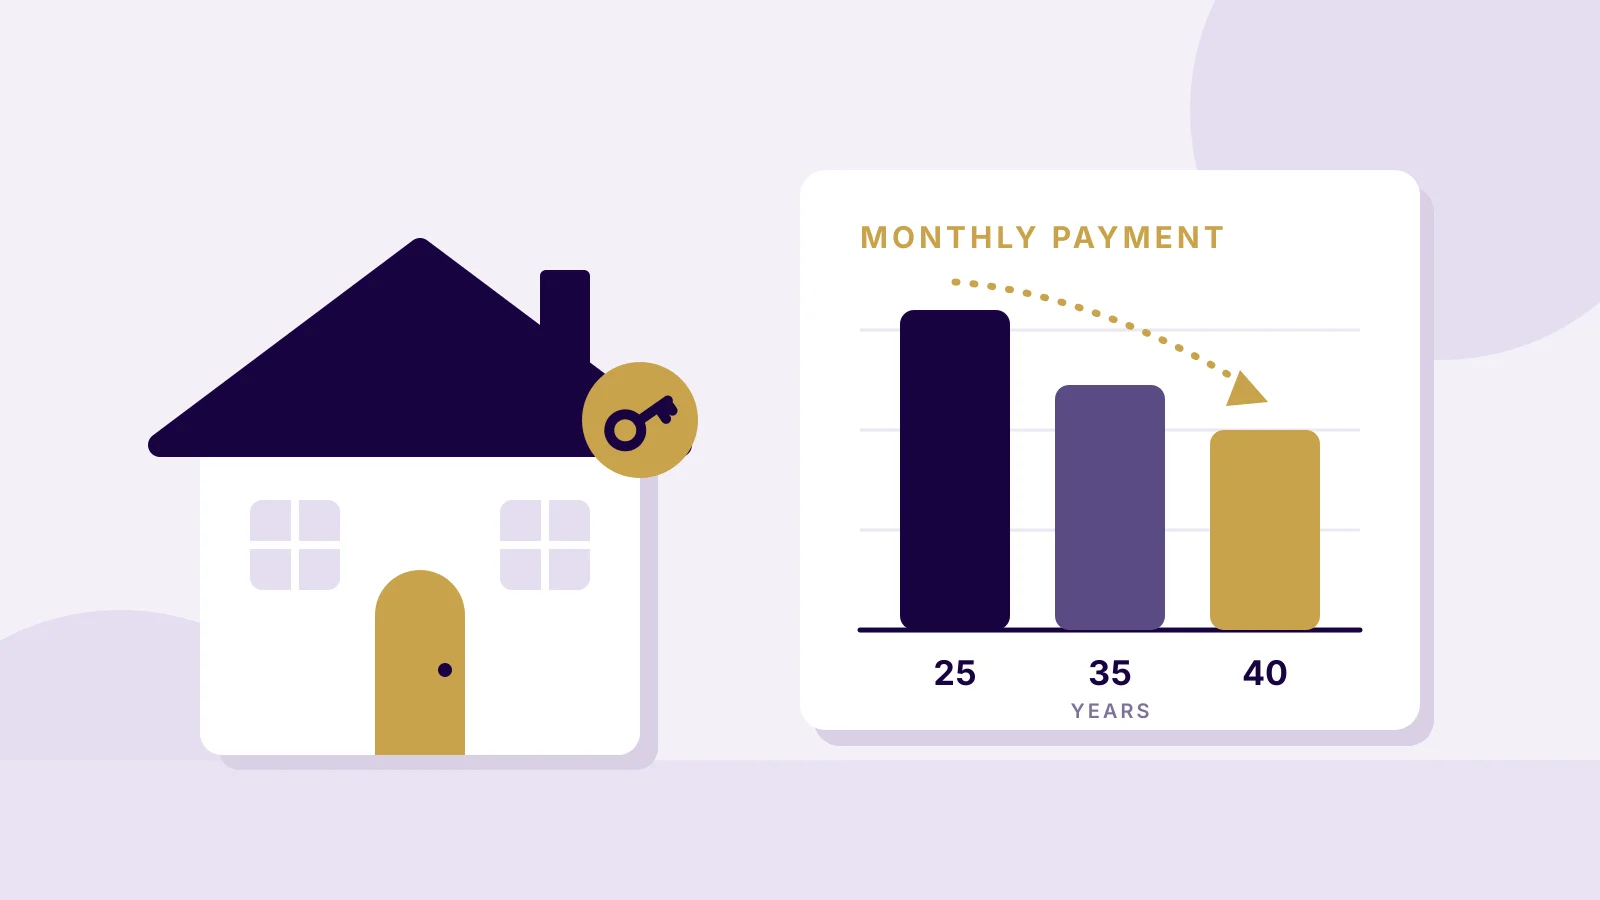
35 & 40-Year Amortization in Canada: How a Longer Mortgage Helps You Qualify
Need a little more room to qualify? Here's how 35 and 40-year amortizations work on conventional mortgages in Canada, what they take today, and what they cost.
Will the Bank of Canada Hike Again on December 9? What Borrowers Should Know
The Bank of Canada's October deliberations show another hike is possible. Here's what a December 9 increase would cost and the data to watch before then.
Markham Home Prices Are Down 6.9% in a Year: What It Means for Your Renewal or Refinance
TRREB's October 2026 data shows Markham's benchmark price down 6.89% from a year ago. Here's what that does to your equity, your renewal and your refinance options.
The Bank of Canada Hiked: Here's What It Means for Your Mortgage
The Bank of Canada raised its policy rate 0.25% to 2.50%, its first hike since July 2023. Prime is now 4.70%. Here's what it means in real dollars, and who feels it.
From Years of Trying to Finally Getting the Keys
A client had a 20% down payment and stable income, but kept hearing "no" from traditional banks. Here's how Pradeepan Suththanantham structured a 35-year amortization through one of Mortgage Made Better's lending partners and helped her become a homeowner.
How to Become a Licensed Mortgage Agent in Ontario: The Complete Step-by-Step Guide and Fee Breakdown
A step-by-step Ontario mortgage agent licensing guide covering FSRA requirements, the Level 1 course, brokerage sponsorship, Triton background check, fees ($941 licence + $19.15 Triton), CE, and the path to Level 2 and Mortgage Broker.
No-Payment Home Equity Options for GTA Homeowners
Access a lump-sum cash advance from your home equity without refinancing, without monthly payments, and without interest — a flexible option for equity-rich GTA homeowners.
Canada's 2026 Real Estate Forecast: What It Means for Buyers, Sellers and Investors
Canada's housing market may gain momentum in late 2026. Learn what today's rates, financing options and Ontario's enhanced new-housing rebate could mean for your next move.
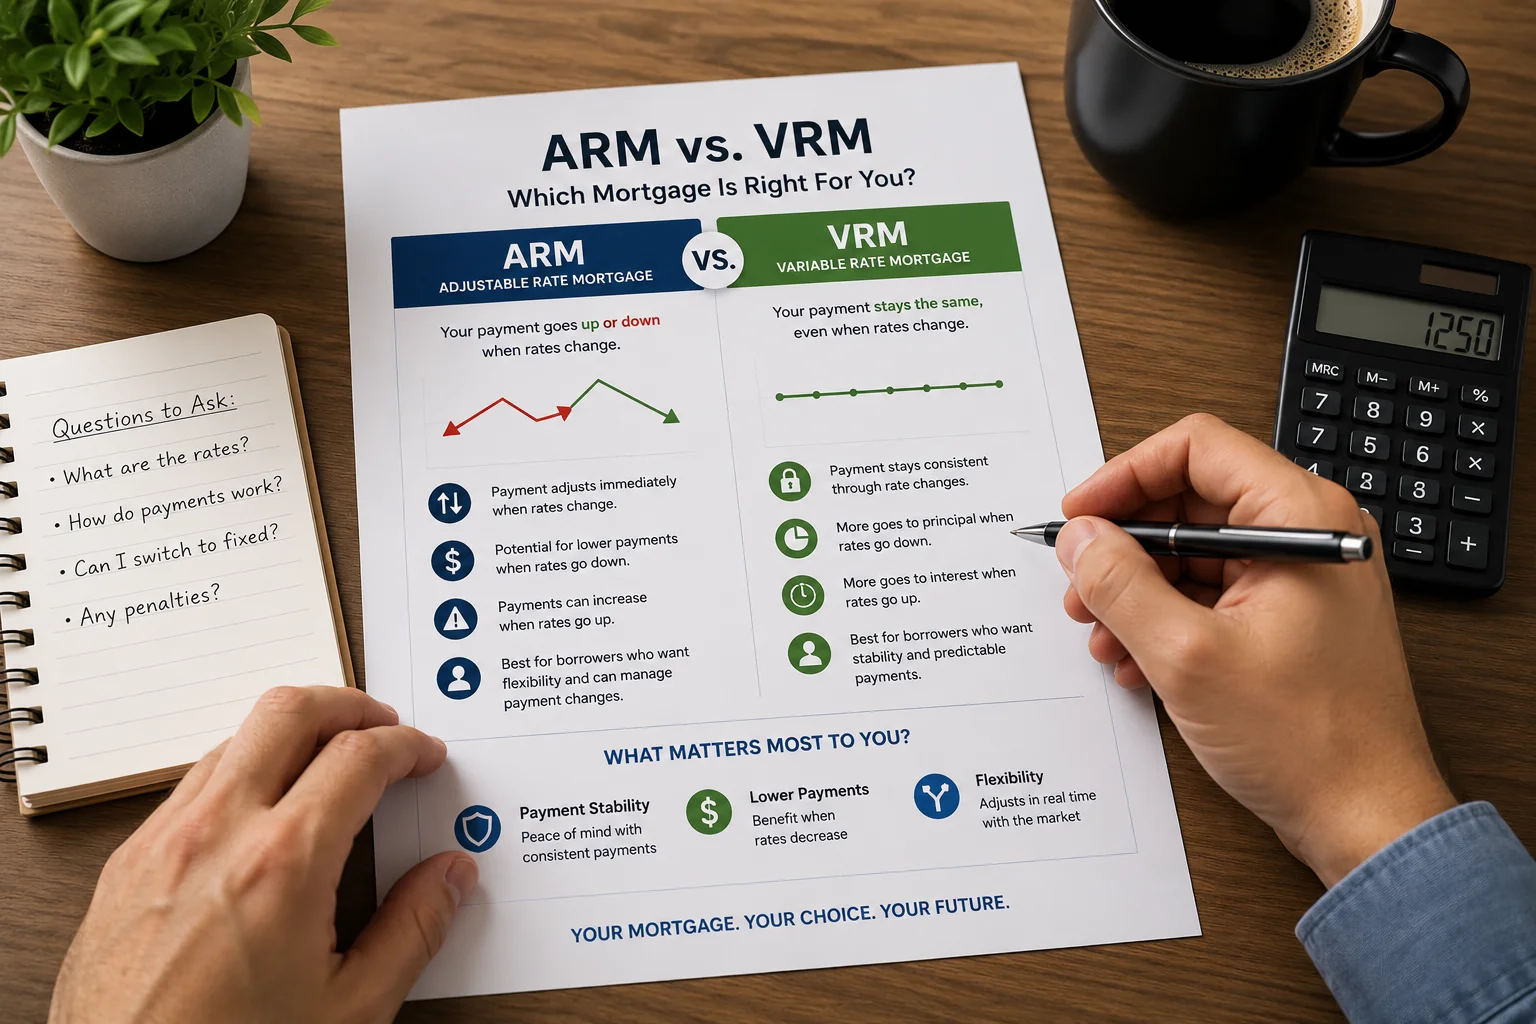
ARM vs. VRM Mortgages in Canada: What's the Difference?
Both move with prime rate — but they behave very differently. Here's the simple breakdown every Canadian borrower should know before choosing a variable product.
The Truth About Mortgage Rates
A rate is not a mortgage. Here's the honest answer on why the fine print matters more than the headline number — and what nearly two decades of experience has taught me.
Income & Down Payment Guide: How Lenders See Your Earnings
Not sure how much you need to put down — or whether your income qualifies? This guide breaks down every income type, minimum down payment requirements, and what documents you actually need.
How We Get You Approved: A Step-by-Step Guide to Working with a Mortgage Broker
A transparent, step-by-step walkthrough of our mortgage approval process — from free consultation to keys in hand — and why working with a broker changes the outcome.
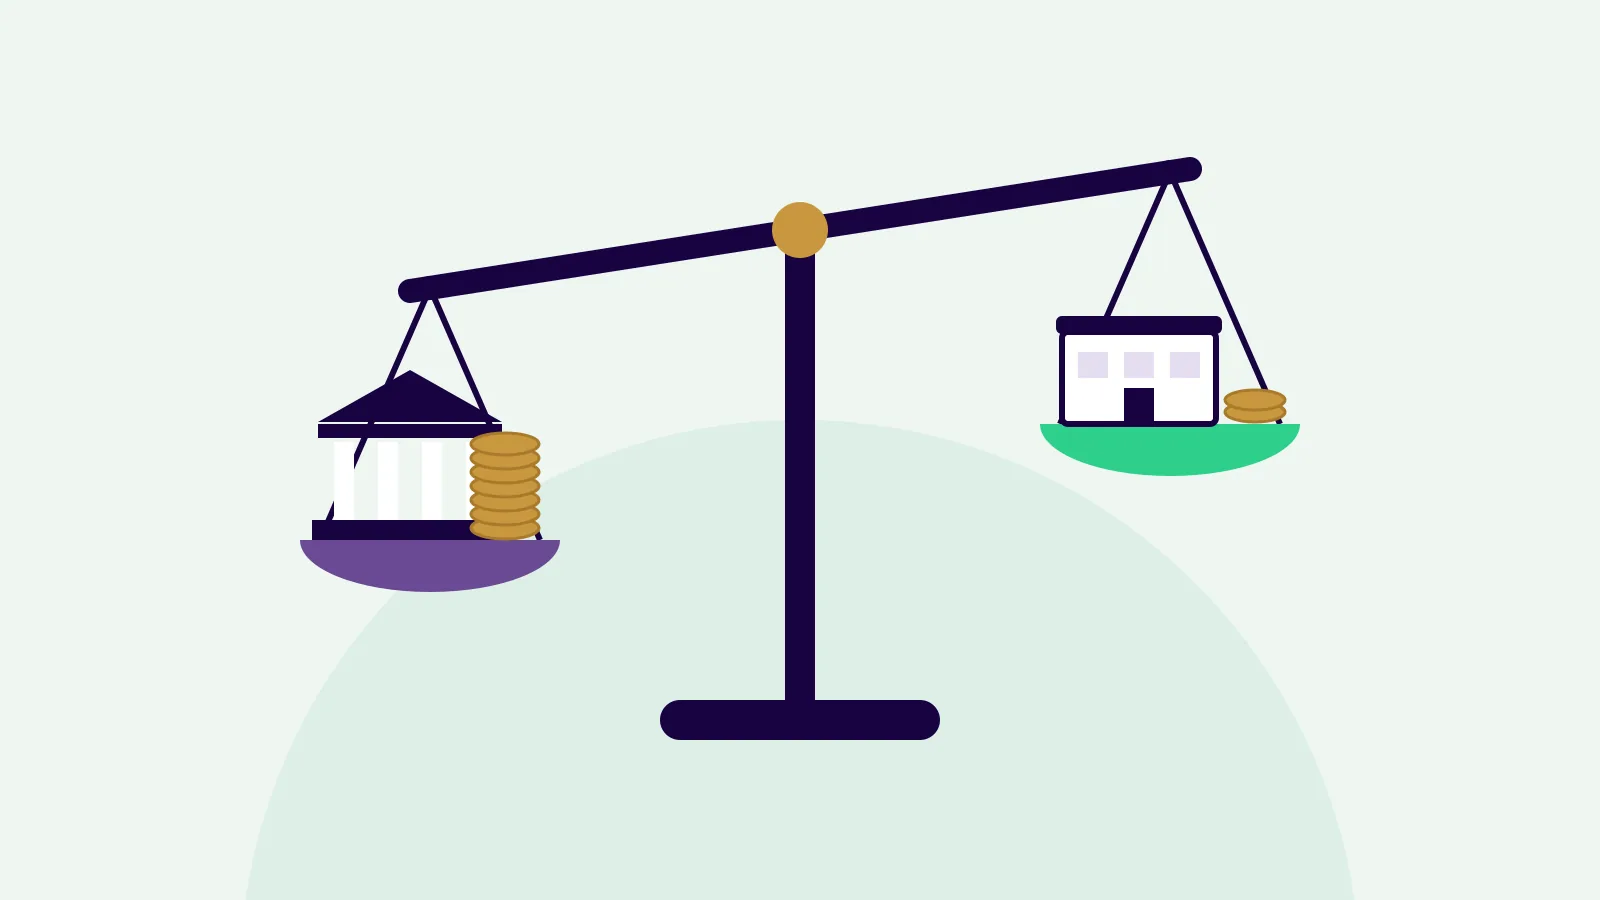
Big Banks vs. Monoline Lenders: Mortgage Penalty Calculations and the Long-Term Savings Case
Most Canadians focus on the rate — but the hidden cost of your lender choice is how penalties are calculated. A $13,500 gap between RBC and MCAP can mean the difference between a profitable refinance and a net loss.
Stop Treading Water: How to Turn Your Debt Around
Drowning in multiple debt payments? See how one client saved $1,300/month by rolling her mortgage, credit line, loans, and CRA arrears into one smart refinance.
Home Equity Loans in Canada: How to Access Your Equity the Smart Way
No-Payment Mortgages Toronto | Deferred Payment Solutions
Flexible terms with deferred payments to relieve cash-flow pressure — ideal for transitions, renovations, or bridging plans.
Land Financing in Ontario: What You Need to Know Before You Buy
Complete guide to financing vacant land in Ontario. Learn about loan-to-value ratios, qualification requirements, and how to structure your land purchase for maximum financing.
Mortgage Renewals & Transfers Toronto | Never Overpay Again
Renewal is your chance to save. We negotiate lenders and rates so you never overpay — even if your situation changed.
Home Equity Line of Credit (HELOC) Toronto | Flexible Access
On-demand access to your home's equity for renovations, investments, or emergencies — with flexible repayments.
Investment Property Mortgages Toronto | Rental Property Financing
Grow your portfolio with smart financing for investment homes, multi-unit buildings, and income properties.
Home Purchase Mortgages in Toronto & GTA
First-time buyer or upgrading? We'll get you the right mortgage with the best terms — making your dream home a reality.
First-Time Home Buyer Programs & Mortgages in Toronto
Tap into Canadian programs like the RRSP Home Buyers' Plan and land transfer tax rebates to enter the market sooner.
Cash-Out Refinance: Access Your Home Equity
Use your home equity to fund renovations, consolidate high-interest debt, or invest in new opportunities.
Ready to make your move?
Our team guides you from pre-approval to closing day — at no cost to you.
No obligation. Takes less than 15 minutes.